
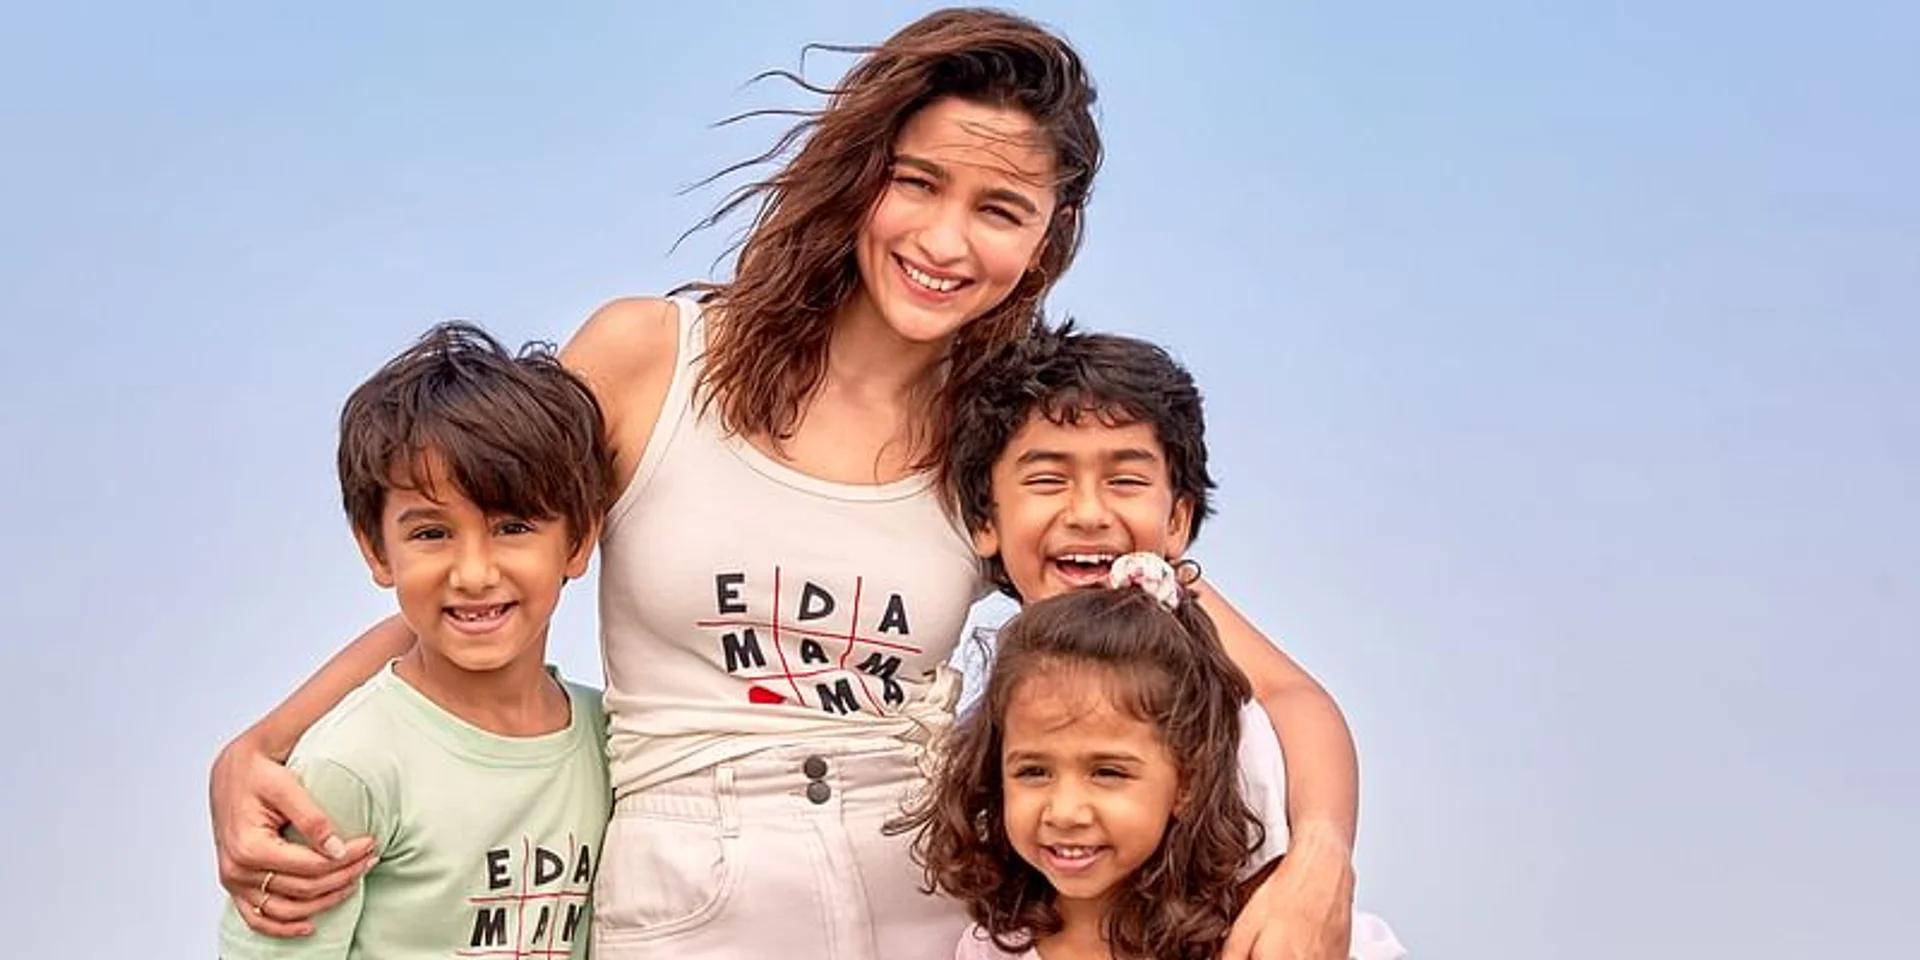
Alia Bhatt built Ed-a-Mamma into a children’s clothing brand with a clear purpose. The business started in 2020 with a focus on kidswear, natural fabrics, nature-based designs, and more responsible fashion. Over time, the brand grew beyond its early product range and entered new areas such as maternity wear, baby care, toys, books, and accessories. This wider product range gives the company more ways to reach families and earn sales.
The brand also gained a major business partner in 2023. Reliance Retail Ventures acquired a 51% majority stake in Ed-a-Mamma. This deal gave the brand access to a large retail network and stronger supply chain support. The partnership marked a major step in its business journey. Yet one key question remains: does Ed-a-Mamma have the financial strength to match its brand appeal? The answer depends on revenue, profit, customer demand, and the cost of future growth.
How Ed-a-Mamma Started and Grew
Alia Bhatt launched Ed-a-Mamma in 2020 with a focus on clothes for children. The brand aimed to offer products that felt comfortable and used nature-based designs. Its early identity also stressed a more careful approach to materials and production. This message helped it stand apart from many basic kidswear labels.
Celebrity fame gave the brand a strong start. Alia already had a large audience, so the company could reach parents through her public image and social media presence. Still, fame alone cannot sustain a retail business. A brand must offer good products, fair prices, reliable delivery, and a clear reason for customers to return.
The Reliance deal in September 2023 marked a major change. Reliance Retail Ventures took a 51% stake and became the majority owner. The partnership gave Ed-a-Mamma a path to wider retail access, stronger supply support, and more reach across India. It also gave Reliance a chance to expand its family and children’s product range through a brand with a clear identity.
Store Growth Shows Wider Reach
Ed-a-Mamma had 12 exclusive stores by June 2026, according to a report from ETRetail. The company reached that total after it added eight outlets across seven cities. The reported locations included Delhi-NCR, Hyderabad, Chennai, Raipur, Varanasi, Lucknow, and Kochi, along with other established markets.
This expansion shows that the brand has moved beyond a digital-first model. Physical stores can help parents check fabric quality, test sizes, compare products, and make faster purchase decisions. Stores can also build trust among families who prefer to see children’s clothes before they buy them.
However, store growth does not prove that sales or profits have risen at the same rate. A store may attract many visitors but still produce weak sales. Rent, staff costs, stock levels, and local demand all affect store profit. The 12-store figure offers a useful sign of expansion, but it cannot replace revenue and profit data.
India’s Kidswear Market Offers Room to Grow
India has a large market for children’s clothing, yet market estimates vary across research firms. IMARC Group estimated the Indian kids apparel market at US$22.57 billion in 2025. Its report projected a compound annual growth rate, or CAGR, of 2.08% from 2026 to 2034.
A separate IMARC report put the Indian kidswear market at US$11.1 billion in 2025 and forecast a CAGR of 4.9% from 2026 to 2034. These estimates use different market scopes and category definitions. They should serve as separate benchmarks rather than figures that can be added together.
A report from the Clothing Manufacturers Association of India, covered by Financial Express in October 2026, projected that the wider Indian apparel market would rise from US$95.7 billion in 2025 to US$146.3 billion in 2029. The report also cited a 9.4% annual growth rate for kidswear. This forecast points to a strong opportunity, but it does not predict Ed-a-Mamma’s own sales.
Children need new clothes as they grow, which creates repeat demand. Parents also buy gifts, festive outfits, school clothes, and daily wear throughout the year. Ed-a-Mamma can benefit from this demand if it offers reliable quality and prices that match family budgets. A large market, however, does not guarantee success for every brand.
Product Prices and Brand Position
Ed-a-Mamma sells products across several price levels. Selected kidswear products appear at prices from about ₹769 to ₹2,299 or more. Selected baby-care products, such as lotion, wipes, massage oil, powder, and detergent, carry listed prices from about ₹269 to ₹599. Selected maternity products range from around ₹599 to ₹4,999, with some marked-down items at lower prices.
These figures show the range of products and prices on offer. They do not reveal the average price that customers pay or the number of units sold. Discounts also make the picture more complex. Some maternity and apparel products have displayed discounts of roughly 30% to 70%.
Retail brands often use discounts to clear seasonal stock, attract new customers, or promote selected products. Such offers do not prove that a brand faces weak demand. However, repeated heavy discounts can hurt profit if customers refuse to pay full price. Ed-a-Mamma must protect its margins while it attracts families and expands its product range.
The Reliance Deal and the Question of Value
The Reliance partnership offers Ed-a-Mamma a major advantage. Reliance has a broad retail presence and strong supply chain capabilities. These resources can help the brand reach more customers and support its move into new cities and product categories.
Some media reports cited a possible valuation or deal size of ₹300 crore to ₹350 crore in 2023. However, the official announcement did not disclose a confirmed deal value. That range should not serve as a verified purchase price or a firm estimate of the company’s worth.
A sound valuation requires more than a celebrity name and a large business partner. Investors need reliable figures for revenue, gross profit, operating profit, cash flow, debt, and future costs. The price paid for a majority stake also does not automatically reveal the value of the entire company.
Ed-a-Mamma does not trade as a separate listed stock on the NSE or BSE. A normal stock market purchase therefore cannot provide direct ownership of the brand. Reliance Industries shares offer exposure to a much larger group, not a direct investment in Ed-a-Mamma alone.
Competition From Established Kidswear Brands
Ed-a-Mamma competes with several brands across online and offline retail. FirstCry offers a broad range of baby and children’s products, from clothes to toys and nursery goods. A 2025 industry publication reported FY2024 revenue of about ₹6,481 crore for FirstCry’s business. That figure covers a much broader operation and does not allow a direct comparison with Ed-a-Mamma.
Hopscotch offers an online-first children’s fashion model, while MiniKlub focuses on infant and children’s clothing. Gini & Jony also has a long history in Indian kidswear. These brands compete for the same family budgets, although their product mixes and business models differ.
Ed-a-Mamma needs more than celebrity reach to win this contest. It must offer a clear reason for parents to choose its products over cheaper alternatives and established labels. Quality, comfort, fit, product design, service, and fair prices can all help build loyalty. A strong brand identity matters most when customers also see real value in each purchase.
The Financial Numbers That Matter Most
The main gap in the investment case lies in the company’s financial data. The available sources reviewed for this report do not establish a reliable year-by-year revenue series for Ed-a-Mamma from FY2021 through FY2026. They also do not confirm its gross margin, operating profit, cash flow, online sales share, or repeat purchase rate.
These figures matter more than store count alone. Revenue growth can look impressive while costs rise even faster. A brand may also report high sales but hold too much unsold stock or spend too much on ads and discounts. Store-level profit can reveal whether each new outlet adds value or creates a financial burden.
A simple example shows the scale of this issue. Twelve stores with monthly sales of ₹20 lakh each would produce annual store sales of ₹28.8 crore. At a hypothetical operating margin of 10%, those sales would imply ₹2.88 crore in operating profit. These figures are only an example, not actual Ed-a-Mamma results. They exclude online sales and assume the selected sales and margin levels hold throughout the year.
The same model also shows why expansion alone cannot prove financial strength. More stores can raise revenue, but they can also increase rent, staff costs, and stock needs. Strong store sales and sound margins must support each new outlet.
Key Risks for Future Growth
Ed-a-Mamma faces several clear business risks. Parents often seek good prices for children’s clothes, and many brands offer similar products. Heavy discounts can lower profit, while poor stock planning can leave a company with clothes that no longer match seasonal demand.
The brand also needs to show that customers return after their first purchase. Alia Bhatt’s fame may attract attention, but repeat sales depend on product quality and customer trust. The move into baby care, maternity wear, toys, and books creates new sales options, yet each category brings its own rivals, costs, and supply needs.
A large retail partner can help with scale, but it cannot remove every business risk. The brand still needs strong demand, careful cost control, and products that earn customer loyalty. Without clear financial records, the size of these risks remains hard to measure.
Is Ed-a-Mamma Worth the Bet?
Ed-a-Mamma has several strengths. It has a known founder, a clear product identity, support from Reliance Retail Ventures, a wider product range, and a reported network of 12 exclusive stores by June 2026. India’s kidswear market also offers room for brands that meet family needs at fair prices.
The main concern lies in the lack of clear public data on revenue, margins, and cash flow. Those gaps prevent a sound estimate of the company’s current value. The brand’s expansion offers a reason for further research, but it does not prove that the business can earn strong returns.
A serious investment review should start with audited financial statements, store-level sales, gross margins, inventory turnover, customer repeat rates, and a confirmed valuation. These figures can show whether Ed-a-Mamma has a strong path to profit or whether growth carries too much risk.
For now, Ed-a-Mamma stands out as a brand with real strategic support and room to grow. Yet its investment case remains unproven until reliable financial data show that sales growth can turn into lasting profit. A celebrity name may open the door, but sound business results must justify the bet.
Also Read – RobCo Crosses $1 Billion as AI Robots Gain Investor Trust